Does Homeowners’ Insurance Cover Garage Door Hail Damage?
Key Takeaways
1. Hail is a covered on most homeowners’ policies, but that does not guarantee a payout.
2. One storm generally means one deductible, not one per damaged item, so filing the door with your roof and gutters gets you past it far faster than filing the door alone.
3. Front Range Raynor performs a thorough inspection ahead of the adjuster’s visit to put your door’s real condition on record if the damage later gets called cosmetic.
Which Part of Your Homeowners Policy Pays for a Garage Door?
Dwelling coverage (Coverage A) pays for a damaged garage door if the garage is attached to your house, and other structures coverage (Coverage B) pays if it’s detached. Coverage A insures the house itself. Coverage B insures buildings on your property that aren’t part of the house, like a detached garage, shed or fence.
Most standard policies cover hail damage to the door either way. What changes is how much money is available to pay for it.
Your dwelling limit is the most your policy will pay to repair or rebuild the house. It’s based on the cost to rebuild, not what the home would sell for. The Insurance Information Institute says detached buildings like a garage are usually covered for about 10 percent of that amount.
The Insurance Information Institute describes the standard arrangement. A homeowner’s policy pays to repair hail damage to the structure. Detached buildings, such as a garage, are usually covered at roughly 10 percent of the amount insuring the house.
| Your Garage | Policy Section | What That Generally Means for a Hail Claim |
|---|---|---|
| Attached to the house | Dwelling coverage, Coverage A | Draws on the full dwelling limit |
| Detached, separated by clear space | Other structures, Coverage B | Often capped near 10 percent of the dwelling limit, shared with sheds and fences |
| Either one, worn or rusted rather than struck | Generally excluded | Wear and tear is a standard exclusion wherever the door sits |
Your insurer may decide the panels were already rusted or corroded before the storm. If so, it can treat the dents as pre-existing damage, meaning damage that was there before the event you’re claiming. Dated photos of your door taken before hail season help you show its condition.
These are general patterns in standard policies, not Colorado-specific rules. Your declarations page controls your claim. It’s the summary page at the front of your policy that lists your coverage limits and deductibles. The full policy wording also applies. That’s the detailed contract that defines what’s covered and what’s excluded.
Why a Cosmetic Damage Exclusion Can Sink a Garage Door Claim
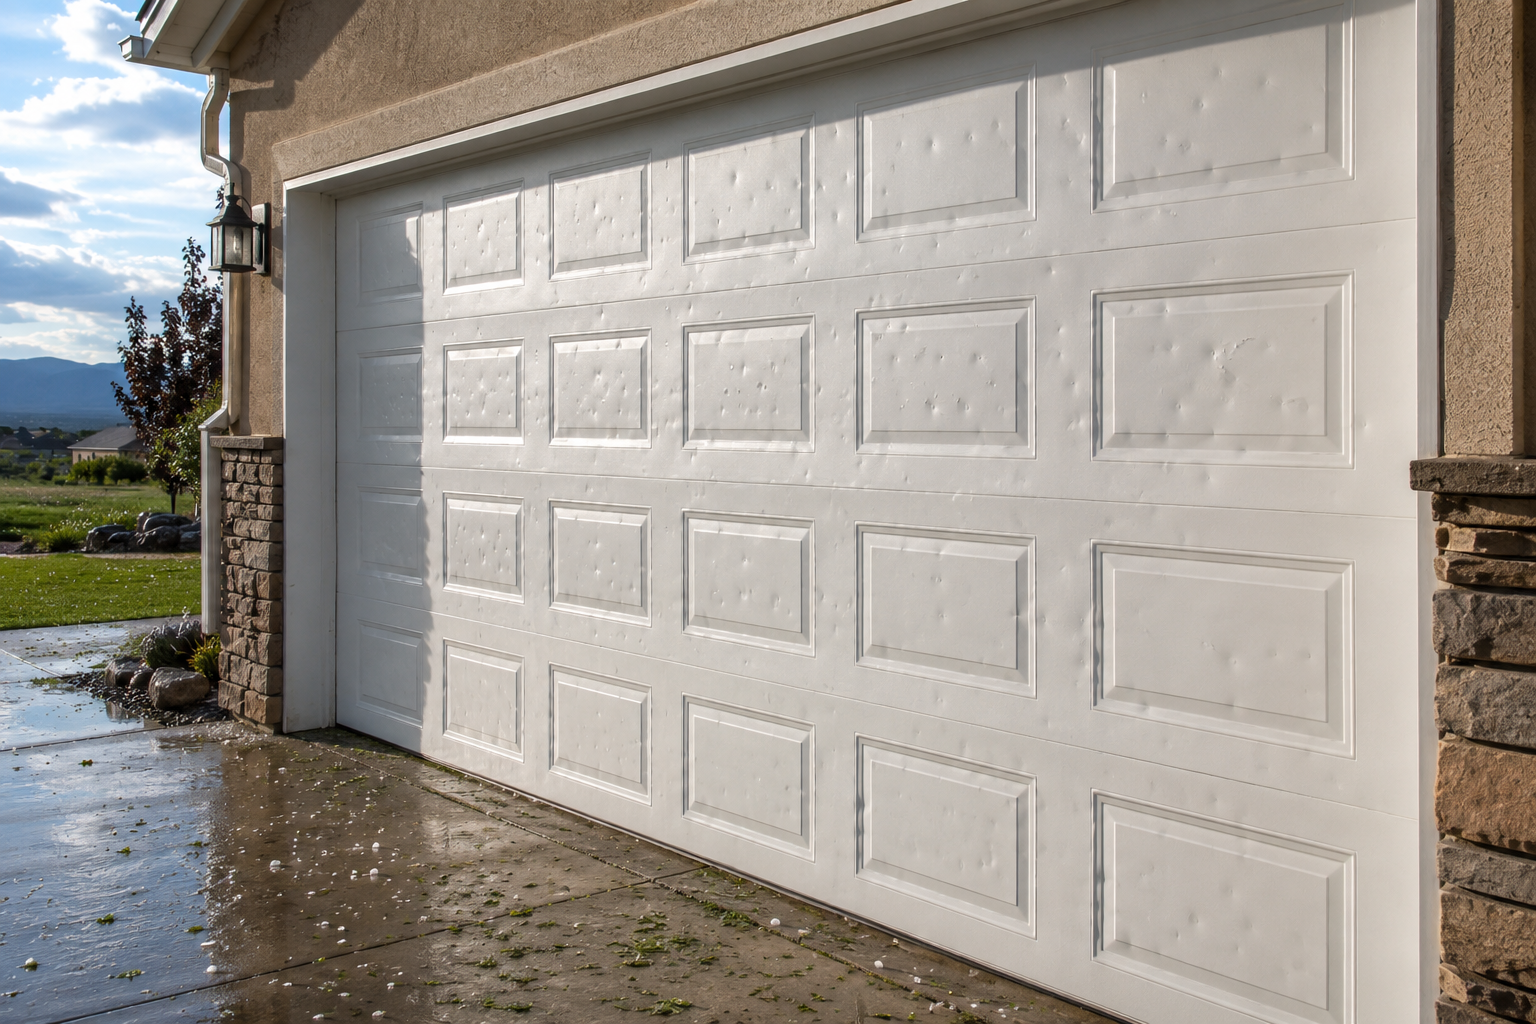
Some policies carry a cosmetic damage exclusion, which lets a carrier decline dents that do not affect how something works. A steel garage door is an obvious target, because a dented panel usually still opens and closes.
Look for that endorsement on your declarations page before you file. If it is there, the argument shifts from how the door looks to how it behaves.
Function is what you document. Binding in the track, sitting off balance, a broken weather seal, or an opener under strain can all evidence functional damage rather than purely cosmetic damage. Whether the exclusion applies still turns on the policy wording and on what caused the condition.
How Does Your Deductible Decide Whether a Garage Door Claim Is Worth Filing?
A covered door does not always mean a paid claim. Many Colorado policies now carry a separate wind and hail deductible, set as a percentage of dwelling coverage rather than a flat amount. Reported figures run between one and five percent, though only your declarations page states yours.
That percentage runs against the cost to rebuild your home. It is not the market price, and it is not the value of the door.
| Deductible Type | How It Is Calculated | What It Means After a Hail Storm |
|---|---|---|
| Flat dollar amount | A fixed figure written into the policy | Predictable, and less common than it used to be in Colorado |
| Percentage of dwelling coverage | A share of the rebuild limit, commonly reported at one to five percent | Scales with the home and can far exceed a flat figure |
Hail also drives a big share of what Colorado homeowners pay. A February 2026 Colorado Division of Insurance survey of 20 carriers found that hail accounts for 26 to 54 percent of a homeowner’s premium, depending on the county.
Larimer and Weld were both surveyed. For Front Range and Eastern Plains counties, the Division put hail’s share of the premium at roughly 50 percent, well ahead of wildfire.
So inventory every damaged surface before you call. Under a single covered loss, the deductible generally applies once to the claim rather than to each damaged item. A claim that includes the door, the roof, the gutters, and the window screens reaches that number far faster than the door alone.
The door also carries evidence. It is usually the largest flat steel surface on a house, and it faces the street. Dents across it help document the size and direction of the storm.
How Common Is Hail Damage Along the Front Range?
Common enough that insurers plan around it every year.
Colorado had 182,591 hail claims between 2013 and 2015, the second-highest total in the country. Only Texas had more.
The pattern held a few years later. The National Insurance Crime Bureau counted 380,066 Colorado hail loss claims from 2017 to 2019, again behind only Texas. Most of those claims were filed under homeowners’ policies, with auto policies next.
Hail also hits harder here than in many places. The Insurance Institute for Business and Home Safety says a 1-inch hailstone falling in Denver carries the same energy as a 1.2-inch stone in Dallas, and that Front Range storms tend to drop more stones per square foot. Researchers haven’t yet shown that the extra energy changes how much damage a surface can take.
So if your door took a hit, you are far from the only one filing. Photograph the damage and report it early.
Northern Colorado's Trusted Garage Door Pros.
Straightforward pricing, expert installation & repair, serving Fort Collins since 1987.
Get a Free Quote
Why Insurers Pay for One Panel Instead of a Whole Garage Door
Sectional doors are built in stacked panels, so a carrier can approve the two dented sections and leave the rest alone.
The Colorado Division of Insurance addresses this in its hail claim FAQs. No law requires a company to match siding or paint on undamaged areas, and a company is required to repair or replace the actual damage the covered event caused.
Read that narrowly. It means there is no general matching requirement, not that a full door replacement can never be owed.
Here is where the distinction bites on a garage door specifically. If your model, panel profile, or factory color has been discontinued, a replacement section will not match the ones above and below it.
Ask in writing whether your exact section is still manufactured before you accept a partial scope. If it is not available, put that in the claim file. It is an argument for replacing the full door rather than patching it, not a guarantee the carrier will agree.
When Should You Report Garage Door Hail Damage in Colorado?
Report it as soon as you can. Most policies require notice as soon as practicable after a loss, and that wording sits in your policy rather than in state law.
Filing a lawsuit is a separate deadline. Under C.R.S. 10-4-110.8(12), a homeowners policy issued or renewed after January 1, 2014, cannot require you to sue in less time than the applicable statute of limitations allows.
Some problems take time to show up, like a door that starts binding or straining the opener weeks after the storm. A late report also lets a carrier blame a different storm.
Is It Worth It to Make an Insurance Claim for Hail Damage?
Filing a hail claim is worth it when the total storm damage to your home costs more than your deductible, and usually not when only the garage door is damaged. Your deductible is the amount you pay before insurance pays anything.
Many Colorado policies have a separate wind and hail deductible. It’s set as a percentage of your dwelling limit, which is the amount your policy insures the house for. It isn’t based on your home’s market price or the value of the door. Reported figures run from 1 to 5 percent.
For example, a home insured for $400,000 with a 2 percent hail deductible has an $8,000 deductible. If the only damage is a dented garage door, the repair probably won’t cost that much, so the claim would pay nothing.
One storm generally means one deductible, not one per damaged item. A claim that includes the door, roof, gutters and window screens reaches the deductible much faster. Have the whole exterior inspected before you decide.
| Situation | Is a claim usually worth it? | Why |
|---|---|---|
| Only the garage door is damaged | Often not | The repair may cost less than a percentage-based deductible. |
| The door, roof, gutters or siding are damaged in the same storm | Often yes | All damage from one storm counts toward one deductible. |
| The door is dented but still opens and closes normally | Check your policy first | A cosmetic damage exclusion lets an insurer deny dents that don’t affect how something works. |
| The door is old and your policy pays actual cash value | The payout may be small | Actual cash value is the replacement cost minus depreciation, the value the door lost to age and wear. |
Claims also affect what you pay later. Your claim history affects your rate and stays with the property. Ask your agent how one hail claim would affect your renewal before you file a small one.
If you decide to file, report the damage soon. Most policies require notice “as soon as practicable” after a loss, meaning as soon as you reasonably can. A late report also lets an insurer blame a different storm.
A covered door doesn’t guarantee a paid claim. Your declarations page shows your actual deductible, so read it before you call your insurer.
What to Do if Your Insurer Denies a Garage Door Hail Claim
A denial is a position, not a verdict. Start by getting the denial in writing along with the adjuster’s photos. The policy language they cite tells you whether you’re fighting a cosmetic exclusion or a coverage question.
From there, you have several ways to push back:
- Ask for a reinspection with your contractor present. Someone who works on doors can show an adjuster the binding and balance problems a photo won’t capture.
- Invoke the appraisal provision. Most policies have one, where each side picks a representative and those two agree on a neutral third.
- File a complaint with the Colorado Division of Insurance, which reviews whether a carrier followed its own contract.
- Consider a claim for unreasonable delay or denial. C.R.S. 10-3-1116 lets a first-party claimant sue in district court for two times the covered benefit plus reasonable attorney fees and court costs, subject to the statute’s own requirements.
Where to Get a Garage Door Hail Inspection in Northern Colorado
Front Range Raynor Garage Door & Service has worked on doors in Fort Collins, Loveland, Greeley, and Windsor since 1987. Our technicians have seen what Front Range hail does to a steel panel.
We’ll tell you straight whether the damage is cosmetic or affects how the door works. You want that answer before an adjuster writes the scope.
If the claim ends in a new door, thicker steel and added bracing hold up better than a thin single-layer panel. You can operate the options yourself at our Fort Collins showroom.
What You Should Do Next
- Pull your declarations page before you call anyone. Find the wind and hail deductible, check whether the structure settles at replacement cost or actual cash value, and look for a cosmetic damage exclusion.
- Photograph the door and record the model label. Shoot each panel in low-angle light so the dents read, then find the data label inside the door, because the model and color are what decide whether a section can be matched.
- Get the door assessed before the adjuster arrives. Request a free quote or reach the Fort Collins showroom, and we will put the condition of your door in writing.